Spanish Market Analysis
Analysis of the Spanish energy market is key to understanding the dynamics and trends affecting the sector both locally and internationally. In this detailed analysis, we address the important factors influencing energy prices, supply and demand, and the latest regulatory policies. This comprehensive overview will allow you to keep up to date with weekly changes and anticipate possible market variations, both in Spain and in other relevant markets such as France.
September 2026
Table of Contents
Key figures of the month
Source: Haya Energy Solutions
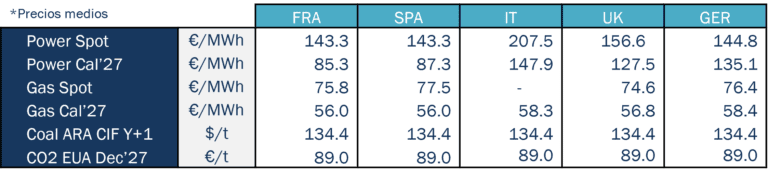
In September 2026, electricity spot prices increased sharply across all major European markets. The upward movement was even more pronounced in the forward market, with Power Cal’27 rising across all countries, largely supported by higher gas prices. Month-on-month increases ranged from c.15 €/MWh in Spain to c.27 €/MWh in Germany, representing a significant repricing over the course of a single month. This broader increase in energy costs also contributed to renewed inflationary pressures in Europe, particularly through higher electricity and fuel prices.
Spain, France and Germany remained in a lower range of monthly average electricity prices, at around 143–145 €/MWh. However, all three markets recorded significant increases compared with August, ranging from approximately 18 €/MWh in Germany to 25 €/MWh in Spain.
By contrast, the UK recorded an average monthly price of around 157 €/MWh, although it experienced the smallest month-on-month increase among the markets analysed. Italy once again stood out as the highest-priced market, averaging around 208 €/MWh, and also recorded the largest monthly increase, rising by approximately 28 €/MWh compared with August.
September also saw new daily solar PV generation records across several major European markets. New highs for a September day were reached in Germany (389 GWh), Spain (267 GWh), France (158 GWh), and Italy (143 GWh). Wind generation, meanwhile, showed significant week-to-week volatility across Europe, becoming an important driver of electricity price movements during the month.
On the gas side, average spot prices stood broadly within the 74–77 €/MWh range across most markets. Compared with August, gas prices increased sharply across all countries, by around 14 €/MWh on average. Gas Cal’27 also moved substantially higher on a month-on-month basis across all markets, with increases of more than 12 €/MWh in each case.
As for CO₂, prices increased from around 85 €/t in August to 89 €/t in September, extending the upward trend observed over recent months. The increase was supported by the broader bullish environment across energy markets, particularly higher gas and power prices. Overall, September was characterised by broad-based upward price pressure across the main energy commodities.
Energy demand and generation mix
Source: Haya Energy Solutions
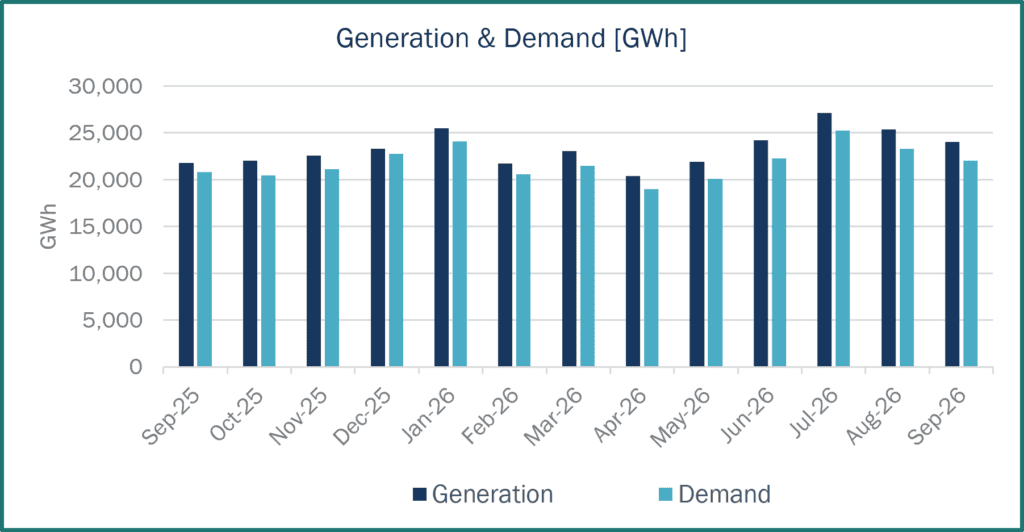
Spanish electricity demand reached 22,000 GWh in September 2026, while total generation stood at 24,000 GWh. Of this volume, around 2,000 GWh was scheduled for export.
Compared with August 2026, both electricity demand and generation decreased. However, on a year-on-year basis, both remained above the levels recorded in September 2025.
Renewables represented 51.1% of Spain’s generation mix in September 2026, down from both 52.9% in August 2026 and 53.1% in September 2025. Solar PV remained the leading generation source, accounting for 26.4% of total output. Although this was below the 29.0% recorded in August, it remained above the 23.2% observed in September 2025.
CCGTs retained their position as the second-largest generation source, accounting for 20.6% of total output. This was slightly below the 21.1% recorded in the previous month, but around 3.5 percentage points higher than in September 2025. Their greater year-on-year contribution was particularly relevant in the context of elevated gas prices, as periods of higher CCGT participation increased the exposure of electricity prices to gas-fired marginal generation. This effect is analysed in greater detail in section 3.
Nuclear ranked third, contributing 20.4% of total generation, above August 2026 (18.8%) but slightly below September 2025 (20.9%). During the month, Ascó I was temporarily disconnected from the grid for maintenance, with no impact on nuclear safety. In parallel, the Spanish Government reiterated that the recently approved extension of Almaraz until June 2030 should not be interpreted as an automatic change to the closure schedule of the remaining Spanish nuclear fleet.
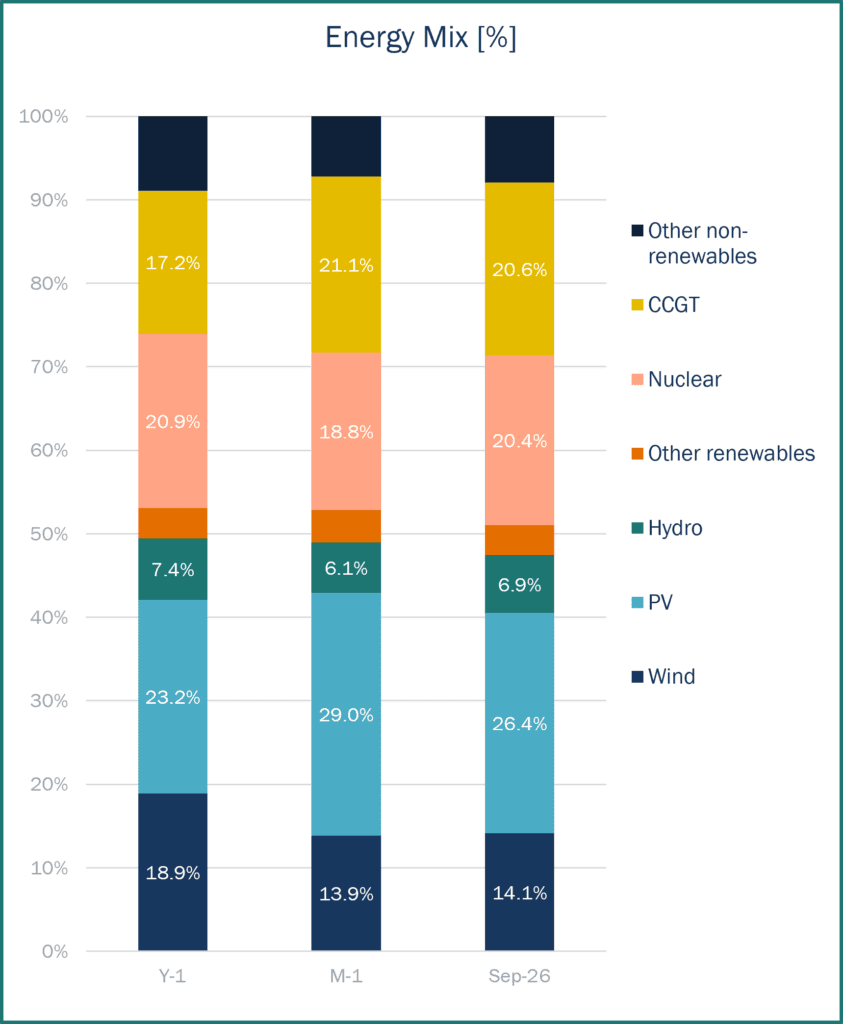
Source: Haya Energy Solutions
Overall, solar PV continued to lead Spain’s generation mix in September, while CCGTs and nuclear contributed at very similar levels, both close to 20%. Despite the decline in solar output compared with August, PV remained clearly above its contribution in the same month of the previous year.
More broadly, the generation structure in September 2026 remained relatively similar to that observed in August, with no changes in the ranking of the three main technologies. The year-on-year comparison, however, shows a more significant shift in wind generation, whose contribution fell by almost 5 percentage points compared with September 2025. This lower wind output reduced renewable availability and increased the system’s reliance on thermal generation, contributing to the upward pressure on wholesale electricity prices observed during the month.
Energy prices & market panorama
Source: Haya Energy Solutions
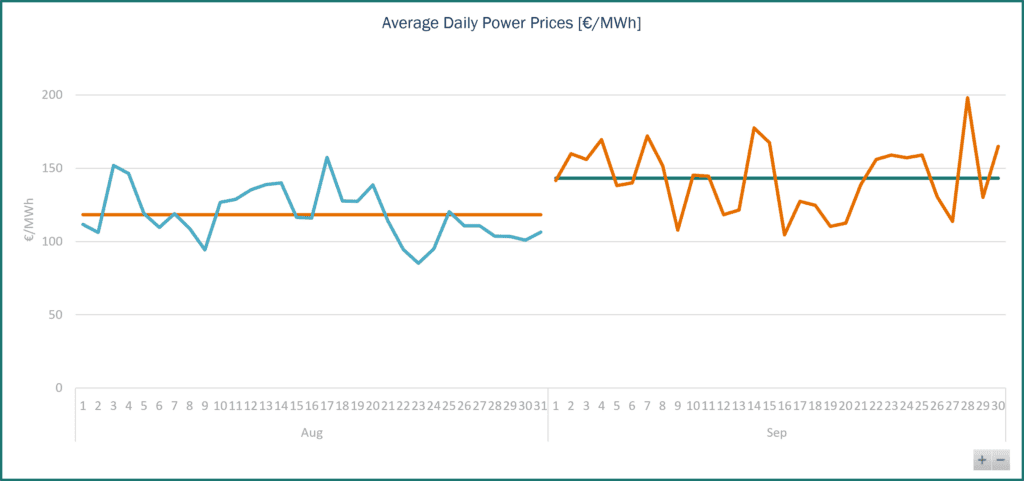
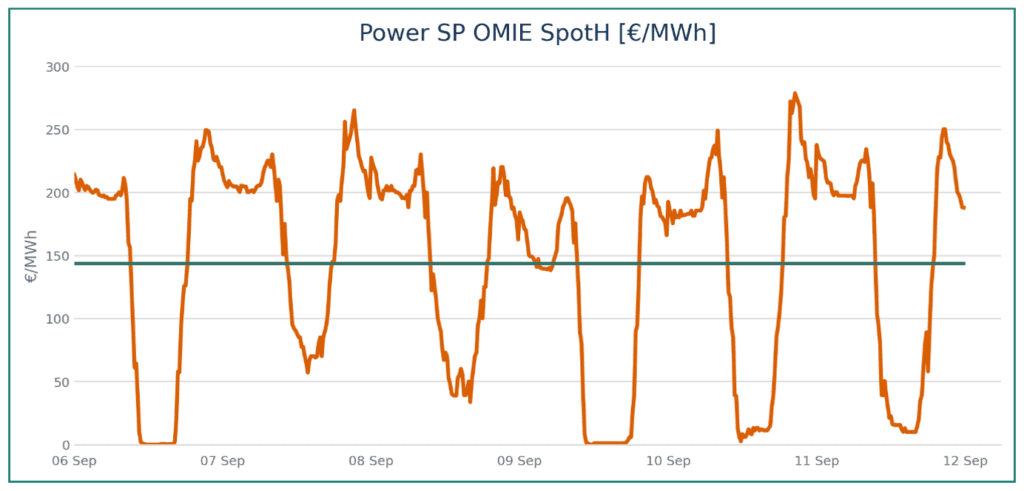
Spain’s average wholesale electricity price stood at 143.25 €/MWh in September 2026, above the 118.24 €/MWh recorded in August. This marked the fifth consecutive monthly increase in the average power price. The intraday pattern highlighted in previous editions remained clearly visible. During the second week of September, prices frequently fell close to 0 €/MWh during the central hours of the day, before rising sharply once solar PV output faded, in some cases reaching or exceeding 250 €/MWh.
Looking at the daily average price profile, all days of the month remained above 100 €/MWh, illustrating the consistently elevated price environment. The monthly daily average peak was reached on 28 September, at close to 200 €/MWh, while the lowest daily average, around 104 €/MWh, was recorded on 16 September. The fact that the daily average approached 200 €/MWh on the highest-priced day of the month provides a clear indication of the degree of market tension during periods of lower renewable availability. Lower wind and solar generation increased the need for gas-fired generation to cover demand, reinforcing the sensitivity of wholesale prices to both renewable output and prevailing gas prices.
Despite the strong increase recorded during the month, Spain remained one of the most competitive major power markets in Europe in terms of average monthly prices. The high penetration of solar PV continued to provide an important price-mitigating effect, particularly when compared with more gas-dependent markets such as Italy, where the average wholesale electricity price reached around 207 €/MWh in September. Notably, even Spain’s highest daily average price during the month remained below Italy’s average price for September as a whole.
On the system operation side, Red Electrica activated the SRAD again in September, bringing the total to nine activations so far in 2026, seven of them since mid-July. The service was called on 4 and 28 September to temporarily reduce demand when available upward reserve was insufficient, with the latest episode linked to lower than expected wind generation. The increasing frequency of these activations highlights the growing role of demand flexibility in balancing a power system with higher renewable penetration and more variable generation.
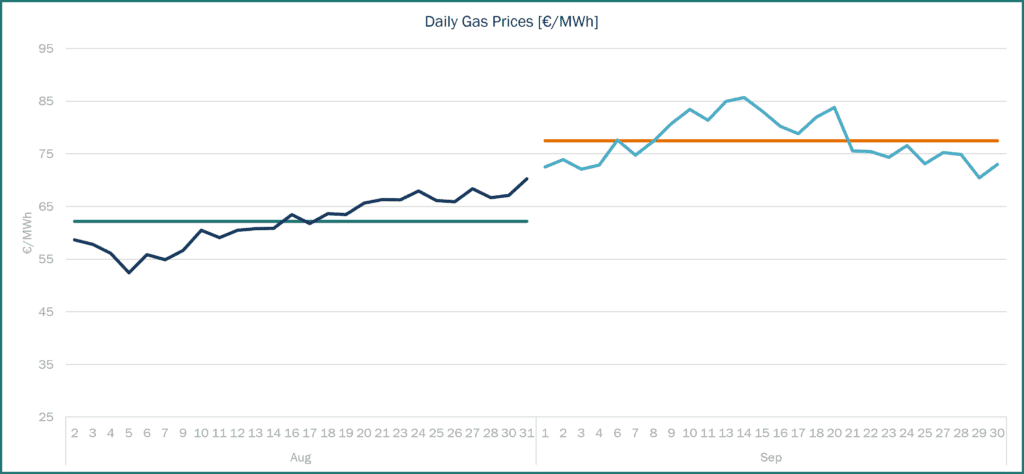
The average natural gas price in the Spanish market stood at 77.45 €/MWh in September 2026, up from 62.18 €/MWh in August, representing an increase of around 25% in a single month. Prices rose sharply during the first half of September, reaching a monthly peak of around 86 €/MWh on 14 September. A moderate downward trend followed during the second half of the month, although prices remained elevated, closing September at around 73 €/MWh.
Source: Haya Energy Solutions
The upward move was mainly driven by persistent geopolitical tensions in the Middle East and continued constraints on global LNG supply. Traffic through the Strait of Hormuz remained restricted, while Qatari LNG flows continued to be affected. At the same time, relatively low European storage levels and stronger gas demand for power generation added further pressure to an already tight market.
During the first half of September, renewed tensions between the United States and Iran increased concerns over energy flows through the Strait of Hormuz. The risk of further disruptions to crude oil supply pushed Brent prices above 100 $/bbl, reinforcing the broader geopolitical risk premium across energy markets. At the same time, restrictions through Hormuz directly affected LNG flows from Qatar and the UAE, adding further pressure to European gas prices and pushing TTF to its highest levels since late 2022. Although prices eased towards month-end, the September average remained significantly above August.
Market trends and futures
Source: Haya Energy Solutions
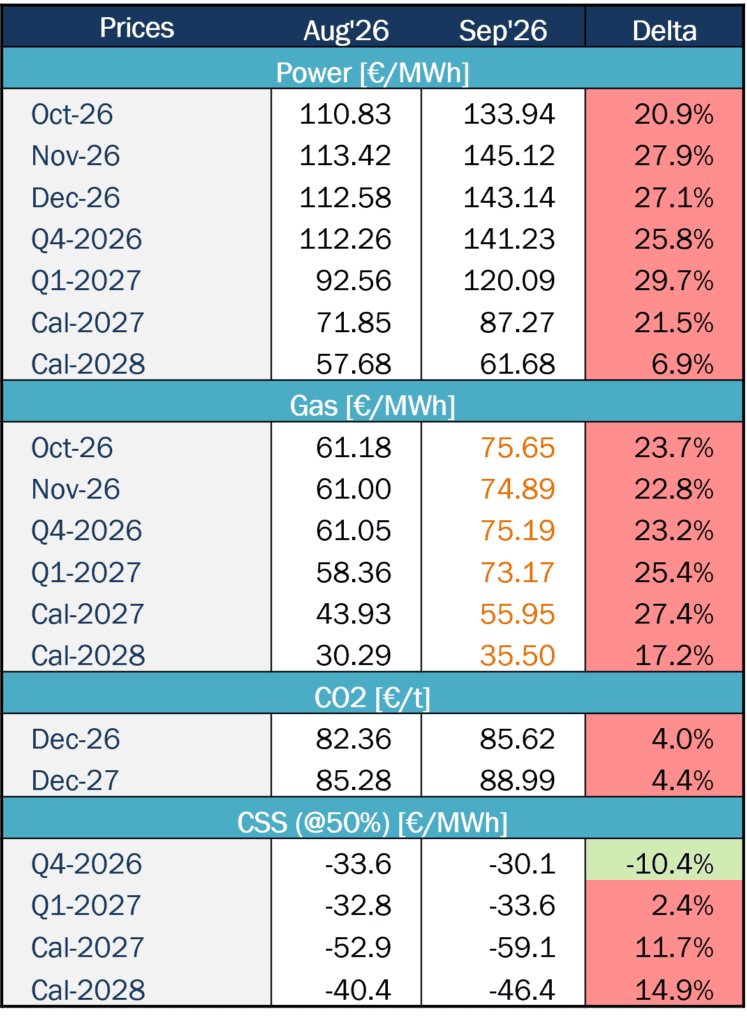
Spanish electricity forward prices moved sharply higher across all products in September 2026, marking the fifth consecutive month of broad-based increases. The strongest gains were concentrated in short- and medium-term products, with all monthly and quarterly contracts under review increasing by more than 20%. Q1-2027 recorded the largest rise, increasing by 29.7% in just one month, while Cal-2027 also moved significantly higher, by 21.5%. The longest-dated product, Cal-2028, increased by a more moderate 6.9%, although this still represents a substantial month-on-month movement for a longer-term contract. Overall, the September repricing indicates that current market pressures are affecting not only near-term expectations but, increasingly, longer-term power price expectations as well.
Gas forward prices also increased sharply across all products compared with the previous month. Near-term monthly and quarterly contracts rose by more than 22%, with Q1-2027 increasing by 25.4%, while Cal-2027 recorded the largest rise, at 27.4%. Even the longer-dated Cal-2028 product increased by more than 17%. This broad-based repricing reflects the persistence of the geopolitical and supply risks described in the previous section, particularly the continued uncertainty surrounding the Strait of Hormuz and its implications for global LNG availability.
Regarding storage levels, natural gas inventories in the European Union currently stand at 71.64% of capacity, around 6 percentage points above the previous month. Despite this improvement, storage remains at its lowest level for this time of year in recent years. In Spain, gas inventories stand at 74.76%, around 1.3 percentage points above the previous month. With the winter season approaching, storage levels remain an important driver of gas price expectations and, indirectly, of winter power prices. In this context, the combination of relatively low European inventories and the recent increase in gas prices adds further pressure to the outlook for the coming months.
CO₂ prices also moved higher during September, extending the upward trend observed over the previous five months. The increase was supported by the broader bullish environment across energy markets, particularly higher gas and power prices, as well as the geopolitical risk associated with developments in the Middle East.